 It pays to pay with Onestpay
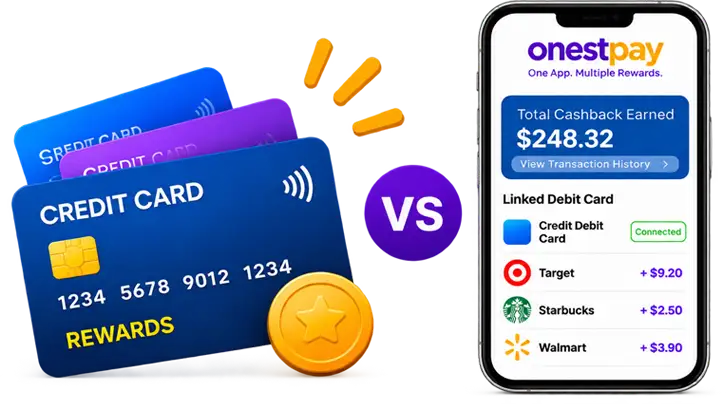
A credit card may advertise 5% cashback. Whether you earn that rate can depend on activating by a deadline, buying from the right merchant, and having room left under a quarterly cap. With OnestPay, you see the participating brand’s cashback offer before you authorize a purchase with your linked debit card.
Which card do you need to earn cashback?
To earn a credit card’s rewards, you need to qualify for that specific card and use it for eligible purchases. OnestPay lets you link an eligible debit card from any U.S. bank or credit union. You can keep the financial institution and checking account you already use.
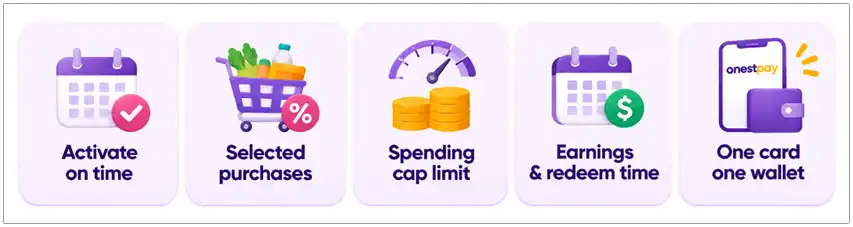
1. You may have to activate before a deadline
One rotating-category card requires you to activate its rotating 5% bonus every quarter. You must activate by the issuer’s deadline to earn that quarter’s 5% rotating bonus. The card’s ordinary rewards still apply under its terms.
Merchant offers can also require action before you buy. Depending on the offer, you may need to activate it and use the same eligible card in-store, or start an online purchase through the offer link. The sampled flat-rate card’s ordinary 1.5% rewards follow the card’s own terms.
2. The higher rate applies to selected purchases
A headline bonus rate can cover specific categories or even named merchants. The rotating-category card changes its 5% categories each quarter. The choice-category card lets you select one 3% category under the sampled standard terms and change it once per calendar month. A purchase has to qualify under the category rules. The way a merchant is classified can affect what you earn.
Merchant offers can change from one visit to the next. One offer may be online-only, another may work in-store, and a third may require you to spend a minimum amount. Keeping up with several programs means checking the current offer, where it works, and when it expires before you pay.
3. Bonus rates can stop at a spending cap
The choice-category sample applies the 3% choice-category rate and 2% grocery and wholesale club rate to the first $2,500 in combined qualifying purchases each quarter. After that, those purchases earn 1%. The flat-rate sample’s 1.5% base cashback is unlimited. Individual merchant offers can have their own limits and conditions.
4. Earning cashback and being able to use it can happen at different times
The rotating-category sample explains that rewards on a purchase made near the end of a billing cycle may show up on the next statement. The sampled merchant-offer program says payouts typically arrive in about 45 days. That timing is for merchant offers. The flat-rate card’s base cashback follows its own rewards terms.
Minimums can also depend on how you redeem. In the choice-category sample, a one-time statement credit or eligible bank deposit has no minimum. A paper check or a contribution to an eligible 529 account starts at $25. The rotating-category and flat-rate cards advertise cash redemption without a minimum.
5. Keep cashback simple with one card and one wallet
At checkout, it can be hard to tell whether you’ll earn the advertised bonus or just the card’s base rate. Did you activate the offer? Does this store or item qualify? Have you already reached the spending cap? If you use several rewards cards, you may have to make that call while shopping and check multiple statements later to see what you actually earned.
With OnestPay, you can review the participating brand’s cashback offer before you authorize the purchase. Use your preferred linked debit card and track the cashback credited for eligible purchases in one OnestPay wallet.
What you have to track at a glance
| What to compare | OnestPay | Credit cards sampled |
|---|---|---|
| Do you have to qualify for a specific credit card? | No. Link an eligible debit card from any U.S. bank or credit union. | Yes. You need the specific card that offers the reward. |
| Do you have to activate rewards each quarter? | No | Yes, for the sampled rotating bonus. |
| Can you miss a bonus by missing an activation deadline? | No | Yes, for the sampled rotating bonus. |
| Do you have to track rotating bonus categories? | No | Yes, for the sampled rotating bonus. |
| Do you have to choose a category to earn a higher rate? | No | Yes, for the sampled choice-category bonus. |
| Can eligibility depend on the merchant or how you shop? | Yes, participating brands and offer terms apply. | Yes, for some bonus categories and merchant offers. |
| Can a quarterly spending cap reduce your bonus rate? | No | Yes, in the sampled rotating- and choice-category programs. |
| Can reward posting depend on a statement cycle or a separate merchant-offer payout schedule? | No, eligible cashback is credited after the purchase is completed and confirmed. | Yes, timing varies by program and offer. |
| Can you review the brand’s cashback offer before authorizing payment? | Yes | Yes, where the issuer displays an applicable merchant offer. |
| Can you earn rewards using your existing linked debit card? | Yes | No, the sampled rewards apply to qualifying credit card purchases. |
How OnestPay works with your existing debit card
OnestPay doesn’t require quarterly activation or rotating category selection. When you’re ready to shop, choose a participating brand and enter the amount in OnestPay. Review the brand’s cashback offer and authorize the payment with your linked debit card. Then use the code at checkout as the brand directs.
Your linked debit card funds the purchase from checking, and the eligible reward goes to your OnestPay wallet after the purchase is completed and confirmed. Check the offer before you pay because rates and brand terms can change. Explore OnestPay cashback